The standard take misses the more important signal underneath. The topic of independent art and the economics of making work deserves more careful attention than the typical coverage provides, and the reason isn’t complicated once you know where to look.
What makes this genuinely different from previous cycles is the Bandcamp and Patreon model that lets direct artist-to-fan economics actually work. Looking back at how we write about these things, the honest but not depressing take on the situation is also the more accurate one once you examine what the evidence actually shows.
The Writing: Setting the Terms
Artist income from streaming platforms averages under $500 per year for the bottom 90 percent. This isn’t just a data point, it’s the structural condition that makes everything else in this analysis make sense. Context like this doesn’t age quickly. The conditions that produced it have been building for years, and their convergence makes the current moment different from previous moments that looked similar from a distance.
The Bandcamp and Patreon model is letting direct artist-to-fan economics actually flourish in ways we haven’t seen before.
Studio space costs in major cities are pricing artists out of urban centres. Artsy contemporary art has been tracking this trend consistently.
What makes this moment worth examining carefully isn’t the novelty but the confirmation. The underlying dynamics have been visible for some time. What’s new is that they’ve reached a threshold where ignoring them requires active effort rather than simple inattention. That threshold crossing is the event, not the underlying movement that produced it.
Artist residency programmes are growing as an alternative to the commercial gallery system, and that’s part of the same picture. These elements don’t exist in separate silos. They’re reinforcing conditions in the same structural shift.
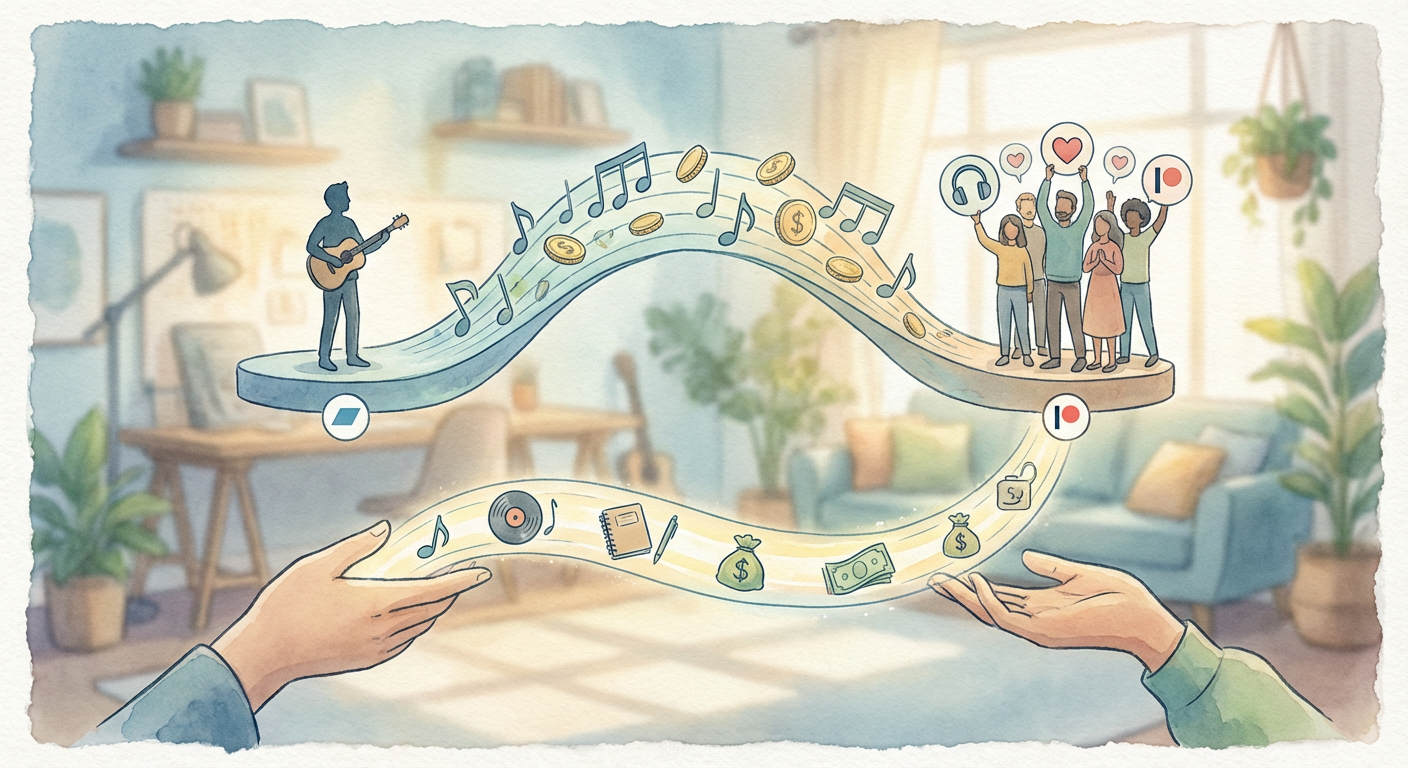
The Obituary Frame: The Analysis
Artist residency programmes growing as alternatives to commercial galleries is where the analysis gets more specific. The surface reading is accessible and not wrong, but it misses the mechanism. The mechanism is where the practical insight lives. What makes this genuinely different from previous cycles: NFT speculation collapsed but the on-chain provenance tools stayed useful. Understanding this changes what you do with the information.
AI image generation is creating new conversations about originality and authorship.
The skeptical counterargument deserves honest engagement. Previous moments with similar surface characteristics didn’t produce the outcomes that seemed logical at the time. That history is real. What’s different now is AI image generation creating new conversations about originality and authorship. This isn’t a minor variable, it’s the infrastructure condition that previous cycles lacked. Infrastructure changes tend to stick around in ways that sentiment-driven changes don’t. Hyperallergic art criticism is one source tracking this with the rigour it requires.
There’s also a distributional question that often goes unaddressed in coverage of independent art and the economics of making work: who captures the value created by these shifts, and who absorbs the disruption costs? The aggregate picture can be positive while the distribution is uneven in ways that matter enormously to specific participants. Keeping that distributional lens in view is part of reading the situation clearly rather than just optimistically.
Implications: What This Means If You Care About Artistic legacies
The implications of independent art and the economics of making work extend beyond the immediate context. Artist income from streaming platforms averaging under $500 per year for the bottom 90 percent, combined with the structural conditions described above, creates a situation where adjacent fields, decisions, and communities get affected in ways that aren’t always visible from inside the primary story. The second-order effects are frequently more important than the first-order ones, and they’re where careful attention pays the highest returns.
The practical question isn’t whether to engage with these dynamics but how. The answer depends on context, on what role you occupy relative to independent art and the economics of making work and what your actual decision horizon is. But the first step is the same regardless: accurate understanding of what’s actually happening rather than what the most available narrative says is happening.
A few concrete observations are worth separating out from the broader analysis. First: the Bandcamp and Patreon model allowing direct artist-to-fan economics to flourish isn’t a temporary condition, it’s a new baseline. Second: NFT speculation collapsed but on-chain provenance tools remaining useful suggests the adjustment period isn’t over. Third, and most important: the organisations and individuals who are treating the current moment as a new steady state rather than a transition are making a categorisation error that will be costly to unwind later.
The Case Against: What the Critics Get Right
Intellectual honesty requires acknowledging the strongest counterarguments, not just the weakest ones. The case against the optimistic reading of independent art and the economics of making work isn’t trivial. There are structural vulnerabilities in the current picture that deserve direct engagement rather than dismissal.
The most serious objection is about sustainability. The cost of studio space in major cities pricing artists out of urban centres can be read not as a foundation but as a ceiling, a point beyond which growth becomes self-limiting because of the very dynamics that produced it. If the current state has already incorporated most of the available supply of early-adopting participants, the remaining growth curve may be structurally shallower than the recent trajectory implies.
AI image generation is creating new conversations about originality and authorship, but these conversations might not resolve in ways that help working artists.
Looking Forward
The trajectory here is clearer than the pace. Making predictions about when specific thresholds will be crossed is genuinely difficult, and anyone claiming precision about timelines should be treated with skepticism. But the direction, toward artist income from streaming platforms continuing to stagnate while alternative funding models develop, is supported by evidence in a way that doesn’t depend on a single variable going right.
AI image generation creating new conversations about originality and authorship is the variable to watch as the leading indicator. Historical patterns suggest it moves first, with broader metrics following with some lag. This doesn’t make the outcome certain, but it makes it legible. And legibility is what you need for good decisions.
Three questions are worth holding as the story develops. First: are the structural conditions that enabled the current state durable, or are they cyclical? Second: who is positioned to benefit from the next phase, and does that differ materially from who benefited in the current phase? Third: what would clean falsification of the optimistic thesis look like, and is there any evidence of that signal emerging? These questions don’t need answers today, but having asked them changes what you notice in the months ahead.
The direction here is clear even when the pace isn’t.
What would you add to the record of what it meant?
